Kenya Payment System Bill 2026 Proposes Major Changes for Banks, Fintechs

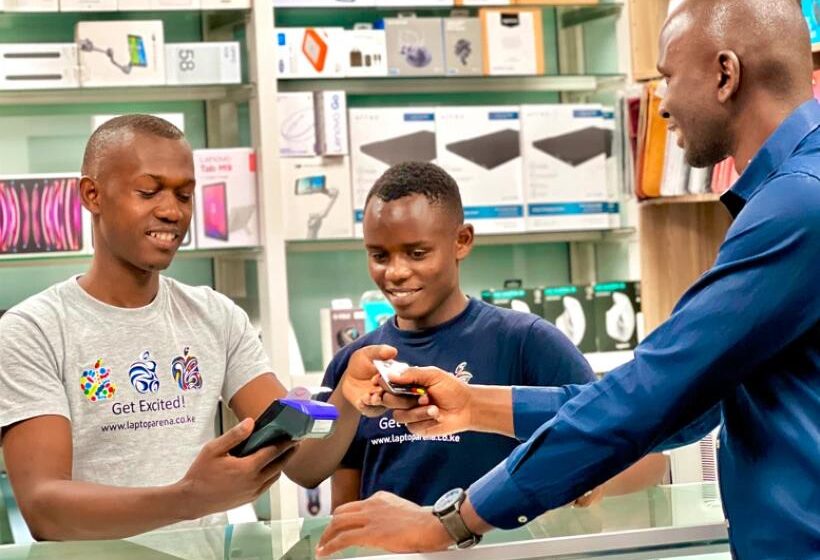
: A Kenyan merchant using a smartphone and point-of-sale payment terminal.
Kenya’s proposed National Payment System Bill, 2026 could reshape the country’s digital payments industry by introducing an open-finance framework, new licensing categories, tiered capital requirements and a regulatory sandbox for innovative payment services.
The draft legislation, developed by the National Treasury in collaboration with the Central Bank of Kenya (CBK), was published for public consultation on September 21, 2026. It proposes to repeal and replace the existing National Payment System Act, Cap. 491A, which provides the current legal framework for payment service providers and payment system operators.
The proposed changes could affect banks, mobile-money operators, fintech companies, digital wallet providers, payment gateways, remittance businesses and technology firms serving merchants. The impact will depend on the final legislation, implementing regulations and the licensing category applicable to each business.
Read Also: Pharmacy Board Looks to Shape Future of Pharmaceutical Practice
The public consultation deadline was October 9, 2026. As of October 25, the proposal should not be treated as enacted law. The Central Bank of Kenya’s official publication outlines the policy objectives, including interoperability, innovation, financial inclusion, consumer protection and financial stability.
Open Finance Could Change How Kenyans Access Financial Services
One of the most significant proposals appears in Clause 29 of the draft Bill, which addresses open finance.
The provision would require payment service providers and payment system operators to maintain systems capable of securely sharing customer data with third parties for open-finance purposes. It would also empower CBK to require providers to implement mechanisms for sharing customer data after obtaining the customer’s consent.
Open finance involves allowing authorised third parties to access and use customer-approved financial information to develop or deliver services. Depending on the final rules, these services could include financial management tools, payment initiation, account aggregation and products that help consumers compare financial options.
For example, a customer who uses several financial providers could potentially access a consolidated view of eligible accounts through a compatible third-party service. A small business might also use authorised financial data to improve cash-flow monitoring or support an application for credit.
These are potential applications rather than guaranteed services under the draft Bill.
The proposal also does not mean that financial institutions would be permitted to disclose customer information indiscriminately. Consent, data security and the applicable legal safeguards would remain central to implementation.
The Data Protection Act, 2019 already establishes obligations concerning the processing and protection of personal data in Kenya. Open-finance arrangements would need to operate consistently with applicable data-protection requirements.
Application Programming Interfaces Could Become More Important
Application programming interfaces, commonly known as APIs, allow different software systems to exchange information through defined technical interfaces.
In a financial-services setting, APIs can enable a customer-authorised application to request permitted information from a bank or payment provider without requiring a separate, manually maintained connection for every transaction.
The proposed open-finance framework could increase the importance of common API standards, secure authentication, access permissions and consistent data formats.
Clause 29 expressly addresses secure data-sharing capability and provides for CBK regulations to implement the framework. The accompanying policy also supports the development of standards for interoperability and innovation.
However, the draft Bill does not itself settle every technical question. The precise API specifications, certification processes, security controls and implementation timetable would depend on subsequent regulations and technical guidance.
Read Also: KNEC Grade 10 Assessment 2026: Guidelines, Timelines & School Requirements
Financial institutions should therefore distinguish between the proposed statutory direction and the detailed standards that would be needed to make open finance work across competing platforms.
Regulatory Sandbox Could Create a Path for Fintech Innovation
Clause 74 proposes a statutory regulatory sandbox framework under which CBK could establish rules allowing eligible businesses limited access to the national payment system to test innovative payment and settlement services without necessarily obtaining a full licence under the proposed law.
A regulatory sandbox is a controlled environment in which a regulator permits qualifying products or services to be tested under defined conditions.
Such an arrangement could benefit fintech firms developing payment solutions that require testing before wider commercial deployment. Start-ups could gather evidence about usability, operational reliability and potential risks while the regulator assesses whether the product can operate safely.
For example, a company developing a new merchant-payment tool might seek permission to test its technology with a limited group of participating businesses, subject to whatever conditions the eventual framework establishes.
The proposed sandbox would not amount to unrestricted permission to conduct payment business. Clause 74 envisages criteria and minimum operating requirements, which would need to be established through the framework.
The practical value of the proposal will depend on eligibility rules, application costs, testing periods, consumer safeguards and the process for moving from testing to full authorisation.
Clear rules would be particularly important for smaller innovators that lack the financial resources of established banks and technology companies.
New Licensing Categories and Capital Requirements
The draft Bill proposes a more detailed licensing structure for payment service providers and payment system operators.
Its First Schedule identifies categories including payment initiation service providers, account information service providers, money remittance service providers, merchant acquirers, electronic wallet providers, electronic money issuers, payment gateways, payment messaging system operators, card scheme operators and payment switching and clearing system operators.
The Third Schedule sets out proposed minimum capital requirements that vary according to the activity being licensed.
| Licensing category | Proposed CBK requirement | Operational and enterprise impact |
|---|---|---|
| Payment initiation service provider | KSh5 million minimum capital | Establishes a capital threshold for businesses facilitating customer-authorised payment initiation |
| Account information service provider | KSh5 million minimum capital | Creates a licensing and capital framework for eligible account-information services |
| Money remittance service provider | KSh30 million minimum capital | Sets a higher proposed capital threshold for money-transfer businesses |
| Merchant acquirer | KSh50 million minimum capital | Raises capital-planning considerations for providers enabling merchants to accept payments |
| Electronic wallet provider | KSh50 million minimum capital | Establishes a proposed threshold for businesses providing electronic wallets |
| Electronic money issuer | KSh250 million minimum capital | Sets the highest listed minimum capital threshold in the proposed schedule |
| Payment gateway | KSh10 million minimum capital | Defines a proposed capital threshold for payment-routing technology providers |
| Payment messaging system operator | KSh20 million minimum capital | Sets a threshold for businesses operating payment-messaging infrastructure |
| Card scheme operator | KSh50 million minimum capital | Establishes a proposed capital requirement for card-network operators |
| Payment switching and clearing system operator | KSh50 million minimum capital | Sets a threshold for operators facilitating payment switching and clearing |
The figures are proposed requirements contained in the draft National Payment System Bill, not new capital rules already in force.
The Bill also addresses businesses operating under multiple licence categories. Its provisions propose that a provider in more than one category would hold the capital required for the highest-capital category, together with 50 per cent of the prescribed minimum for each additional licence category.
This could affect companies whose services span several regulated activities. Businesses may need to review their corporate structure, capital plans and product portfolios once the final requirements are known.
CBK Approval for Mergers and Ownership Changes
The draft Bill also proposes tighter controls over changes in ownership of regulated payment businesses.
Clause 57 states that a merger or acquisition involving a payment service provider or payment system operator would require prior written approval from CBK, subject to the Competition Act. The approval procedure would be provided for in regulations.
Read Also: Top Comoros Official Hospitalized in Nairobi Amid Rising Tensions in Moroni
Clause 58 separately addresses significant ownership changes. Under the draft, an incoming shareholder intended to hold at least 10 per cent of a provider’s shares, directly or indirectly, would trigger the proposed significant-change-of-ownership provisions and prior written approval requirements.
These provisions could influence acquisitions, investment rounds and restructuring transactions involving payment companies.
Investors would need to consider regulatory approval alongside commercial due diligence, competition requirements and transaction timelines. Fintech founders could also face additional planning requirements when bringing in investors whose holdings meet the proposed threshold.
The provisions remain subject to the legislative process and any changes made before enactment.
Consumer Protection, Security and System Interoperability
The proposed overhaul extends beyond licensing and investment.
Clause 28 addresses interoperability, requiring compatible systems and allowing CBK to direct providers to enter into interoperability arrangements under the proposed framework. Greater interoperability could make it easier for payment systems to communicate and support transactions across providers.
Clause 27 also addresses market conduct, including customer-data protection and accessible complaint-handling mechanisms.
The Bill contains additional provisions on trust arrangements, payment transparency, reporting, inspections and regulatory enforcement. Together, these proposals seek to strengthen oversight of a sector in which service interruptions, fraud and poor handling of customer information can have immediate financial consequences.
Implementation will matter as much as the statutory language. Interoperability must be supported by dependable infrastructure, effective dispute resolution, appropriate cybersecurity and clear responsibility when a transaction fails.
Consumers should not assume that the draft guarantees lower fees or eliminates payment fraud. Those outcomes would depend on how the final rules are designed and enforced, as well as how providers respond to the new framework.
What Fintech Companies and Banks Should Do Next
Financial institutions should continue complying with the laws and CBK requirements currently in force while monitoring developments concerning the proposed Bill.
Businesses can begin by mapping their existing products against the draft licensing categories. They should assess whether their current activities could fall under more than one category and review the proposed capital requirements against their financial plans.
Technology teams can also evaluate data-sharing architecture, customer-consent processes, access controls and API readiness. Such preparation may reduce implementation pressure if open-finance requirements are adopted, although companies should avoid investing on the assumption that every draft technical proposal will remain unchanged.
Legal and compliance teams should monitor the development of regulations covering open finance, the sandbox, ownership changes and licensing. Firms considering mergers, acquisitions or new product launches should obtain appropriate professional advice before relying on proposed rules as though they were already operative.
The public consultation period has closed, but that does not establish that the Bill has been enacted. The next important developments are the publication of any revised proposal, its progress through the relevant law-making process and the release of implementing regulations.