National Payment System Bill 2026: CBK Seeks Stronger Powers to Inspect Payment Firms, Remove Executives

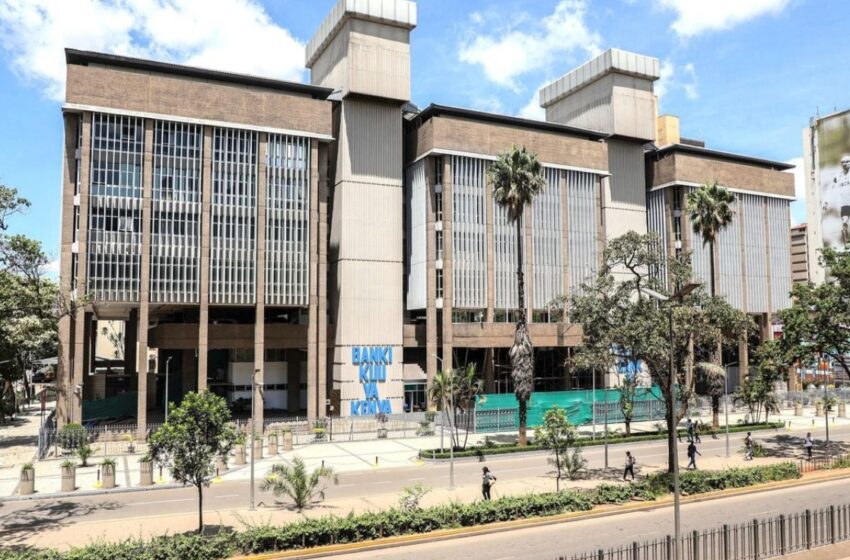
The Central Bank of Kenya headquarters in Nairobi. (Photo: CBK)
Kenya’s digital payments industry could face a tougher regulatory environment if the proposed National Payment System Bill 2026 becomes law, with the Central Bank of Kenya (CBK) seeking wider powers to inspect payment companies, examine records and intervene in the management of firms that breach regulatory requirements.
The proposed legislation seeks to replace the National Payment System Act, 2011, with a broader framework covering payment service providers, payment system operators, electronic money issuers, payment gateways and other businesses supporting the country’s digital payments infrastructure.
The Central Bank of Kenya says the proposed framework is intended to strengthen safety, efficiency, competition, innovation and consumer protection within the national payments ecosystem.
PAY ATTENTION: Follow Kenya Frontline WhatsApp channel for more news
Digital payments have expanded rapidly, making regulatory oversight increasingly important. Mobile money platforms, fintech companies, payment gateways and electronic money providers now process large volumes of transactions every day, creating risks that can extend beyond individual companies to the wider financial system.
CBK Inspection Powers Could Become More Extensive
One of the most significant provisions contained in the National Payment System Bill 2026 concerns the inspection powers available to the CBK.
Clause 20 proposes allowing authorised CBK officers, with or without prior notice, to enter and inspect premises occupied by payment service providers, payment system operators and their agents.
Inspectors would be able to examine books, accounts, documents, equipment, records and other materials considered necessary to determine whether a regulated entity is complying with the law.
The provision could give the regulator greater flexibility when dealing with suspected breaches. Instead of waiting for a scheduled inspection, authorised officials could undertake an inspection where circumstances require immediate regulatory attention.
Such powers would be particularly significant within the fintech sector, where important business operations may be distributed across physical offices, cloud infrastructure, third-party technology providers and data centres.
A payment company could therefore face scrutiny extending beyond its offices to systems and records supporting its payment operations.
Database Records and System Audits
The proposed law also places greater emphasis on technology systems and the information held by payment providers.
Regulated firms could be required to provide documents, records and information needed by the CBK to perform its supervisory responsibilities.
The proposed framework also gives the regulator powers connected to anti-money laundering, combating terrorism financing and countering proliferation financing.
System audits are another major component of the Bill.
Under the proposed provisions, the CBK could direct a payment service provider or payment system operator to conduct a system audit and submit records or information considered necessary by the regulator.
Annual system audit reports would also become an important compliance requirement, with audits undertaken by auditors approved by the CBK.
Read Also: Pharmacy Board Looks to Shape Future of Pharmaceutical Practice
A system audit under the proposed framework would examine operational and management systems, including data integrity, protection of assets, efficiency and the company’s ability to identify and address weaknesses.
The approach places cybersecurity, data protection and operational resilience closer to the centre of payment-sector regulation.
Executives Could Face Removal Over Regulatory Breaches
Executive accountability represents another major area addressed by the proposed legislation.
The Bill gives the CBK powers to intervene in the management of a payment service provider or payment system operator where the institution fails to meet customer obligations, financial obligations or regulatory requirements.
Regulatory intervention could include directing the removal of an officer or employee considered responsible for, or to have contributed to, a breach or deterioration in the financial or operational position of the institution.
The regulator could also appoint a qualified person to a company’s board, restrict the provider from conducting certain payment business, revoke specific mandates and impose restrictions relating to agents.
Such provisions could significantly change governance expectations within Kenya’s fintech industry.
Directors and senior executives would face greater pressure to ensure that their institutions maintain adequate compliance systems, financial controls and operational safeguards.
The proposed framework also provides for fit-and-proper requirements, meaning individuals occupying senior positions within regulated payment businesses could face greater regulatory scrutiny.
Protecting Customer Funds
Customer protection sits at the heart of several provisions contained in the proposed Bill.
A payment provider facing serious financial or regulatory problems could become subject to intervention designed to protect customer funds and maintain settlement operations.
Where a licence is suspended or revoked, the CBK could take control of assets for purposes connected to protecting customers and ensuring the orderly settlement of obligations.
The proposed legislation also provides for the appointment of a statutory manager in certain circumstances.
Customer funds held by electronic money issuers would receive particular protection under the proposed framework. Money belonging to customers would be required to be held in trust arrangements, helping separate those funds from the provider’s ordinary business assets.
Such safeguards could become especially important if a payment company becomes insolvent or experiences serious operational difficulties.
New Compliance Demands for Fintech Companies
Payment providers would face a broader compliance framework if the Bill becomes law.
Requirements would cover areas such as licensing, capital requirements, corporate governance, record keeping, cybersecurity, system audits, outsourcing arrangements, agency relationships and consumer protection.
Payment gateways would also fall within the broader regulatory framework because of their role in processing, routing and facilitating electronic transactions.
The changes could therefore affect a wide range of businesses rather than only traditional mobile money operators.
Digital lenders that operate payment infrastructure, fintech platforms, electronic money issuers and companies providing payment technology could all need to review their licensing and compliance arrangements.
The proposed framework also addresses interoperability and open finance, reflecting the growing connection between payment systems and other areas of digital financial services.
What the Bill Means for Digital Payments
The proposed legislation comes as digital transactions become increasingly important to the economy.
Mobile money, online payments and fintech services have transformed how consumers and businesses move money, but the expansion has also created new regulatory risks.
A major cyberattack, prolonged system failure, governance breakdown or financial crisis at a significant payment provider could disrupt thousands of businesses and millions of customers.
Stronger CBK monetary oversight would give the regulator additional tools to identify weaknesses and intervene before problems become broader financial stability concerns.
The proposed inspection and enforcement powers, however, are likely to attract significant attention during the legislative process.
Read Also: Kenyan marathoner remanded over Ksh8 million land fraud case
Issues surrounding due process, confidentiality, executive rights, access to commercial information and the extent of regulatory intervention could become important points of discussion among payment companies and other stakeholders.
The National Payment System Bill 2026 remains a proposed law and could still change through public participation and parliamentary consideration.
Its direction nevertheless signals a significant shift in the regulation of digital payments. Payment companies would increasingly be judged not only on their ability to process transactions but also on governance, cybersecurity, financial resilience, customer protection and compliance.
A stronger statutory framework could give the Central Bank of Kenya wider authority over the country’s rapidly evolving payments ecosystem while placing greater responsibility on executives running fintech and payment businesses.