National Assembly State Asset Oversight 2026: Kenya Pipeline Company Stake Acquisition Transparency Audits

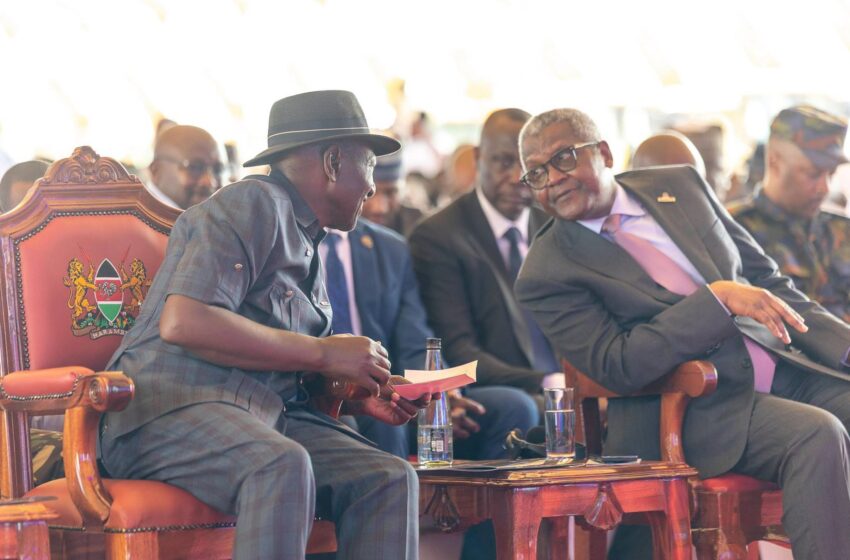
President William Ruto and Aliko Dangote . IMAGE:PPU
Sale of a 24.76 per cent stake in the Kenya Pipeline Company (KPC) to industrialist Aliko Dangote has intensified debate over public asset valuation, institutional accountability and the management of state-linked investments.
The transaction, valued at approximately KSh42.5 billion, involved about 4.5 billion shares previously held by public institutions. Dangote confirmed the acquisition on October 21, 2026, placing the transaction at the centre of discussions about Kenya’s privatisation programme and the role of public institutions in the country’s capital markets. Details of the deal have been reported by Reuters and other financial news outlets.
The acquisition has raised questions about the price received by the selling institutions, the valuation methods applied and whether the interests of the public were adequately protected. National Assembly scrutiny associated with Kiharu MP Ndindi Nyoro has brought renewed attention to the need for disclosure concerning the National Social Security Fund (NSSF), the Unclaimed Financial Assets Authority (UFAA) and other public entities that invested in KPC.
Read Also: KNEC Grade 10 Assessment 2026: Guidelines, Timelines & School Requirements
At the heart of the debate is a straightforward issue: did the institutions receive fair value for the shares, and can the public independently verify the decisions that led to the transaction?
Why the Kenya Pipeline Stake Sale Matters
KPC operates critical petroleum transportation, storage and distribution infrastructure serving Kenya and regional markets. Its pipeline network connects the Port of Mombasa to inland destinations, making the company an important part of the country’s energy supply chain.
The acquisition of a substantial shareholding by Dangote could support additional investment in petroleum infrastructure and strengthen regional commercial links. However, those potential benefits do not remove the need for scrutiny of the sale.
The transaction followed KPC’s initial public offering in early 2026, through which the government began reducing its ownership in the company. The official KPC IPO information memorandum provides a reference point for examining the original offering, its terms and the ownership arrangements disclosed to investors.
Public reporting indicates that several state-linked institutions acquired significant shareholdings during the IPO after private investor demand fell short of the government’s expectations. Those institutions subsequently participated in the reported block sale.
This sequence has raised questions about the timing of the investments, the financial exposure of the institutions and the process used to determine the final selling price.
Read Also: Top Comoros Official Hospitalized in Nairobi Amid Rising Tensions in Moroni
A proper assessment must consider more than the difference between the original offer price and the eventual sale price. Relevant factors include the acquisition cost, transaction expenses, dividends received, the shares transferred and the valuation of KPC at the time of disposal.
Ndindi Nyoro’s Call for Transparency
Parliamentary scrutiny has focused attention on the responsibility of public institutions to demonstrate that investment decisions are made in accordance with their legal mandates and financial obligations.
NSSF manages retirement savings on behalf of members and employers. Its investments must be assessed against its statutory responsibilities, applicable investment rules and the need to protect members’ long-term financial interests.
UFAA has a different mandate. It administers qualifying unclaimed financial assets under the applicable legislation and is responsible for safeguarding those assets while facilitating their return to rightful owners.
The two institutions should not be assumed to have identical financial interests in KPC. Their individual shareholdings, transaction approvals and proceeds should be established through official records.
Legislators seeking greater disclosure need access to the number of shares held by each institution, the amount originally invested, the selling price, transaction costs and the proceeds received.
The inquiry should also establish whether independent valuations were undertaken, which advisers participated in the transaction and whether the relevant institutional boards approved the disposals.
These records would help Parliament determine whether the sale was consistent with the interests of pension contributors, beneficiaries of unclaimed assets and other stakeholders.
Legal Framework Governing Public Asset Sales
Kenya’s laws establish principles and procedures for managing public resources and disposing of assets. The applicable requirements depend on the ownership of the shares, the legal status of each seller and the structure of the transaction.
Article 201 of the Constitution
Article 201 of the Constitution of Kenya sets out principles of public finance, including openness, accountability, prudent financial management and responsible use of public money.
These principles provide an important foundation for examining transactions involving public resources.
In the KPC case, accountability requires sufficient information to establish the financial interests held by public institutions, the basis for the valuation and the consideration received from the sale.
Commercial confidentiality may protect legitimate business information, but it should not become a blanket reason to prevent scrutiny of transactions involving public assets.
Parliament must balance legitimate commercial interests with the public’s right to understand how institutions have managed investments entrusted to them.
The Privatization Act, 2025
Kenya’s current statutory framework includes the Privatization Act, 2025, which provides for the country’s privatisation processes.
The relevance of this legislation to the KPC block sale must be assessed against the transaction’s legal structure. A transfer of existing shares between shareholders may raise different questions from the government’s original disposal of shares through an initial public offering.
Parliament should establish the applicable legal route, the approvals required and whether the transaction complied with the relevant statutory provisions.
The legal character of the transaction matters because a sale involving government-owned shares may be subject to different requirements from a disposal undertaken by a separate institution under its own investment mandate.
Public Procurement and Asset Disposal Act
The Public Procurement and Asset Disposal Act, 2015 governs public procurement and the disposal of public assets within its scope.
Its application to the KPC share sale should be determined by examining the asset involved, the identity of the seller and the governing legal arrangements. Not every transfer of shares automatically falls under the Act’s ordinary disposal procedures.
Where applicable, the relevant requirements concerning disposal methods, valuation, approvals and accountability must be observed.
The central task for Parliament is to identify the legislation governing each institution’s actions and determine whether the transaction complied with those requirements.
KPC Stake Sale: Institutions Under Scrutiny
The reported transaction involved a combined 24.76 per cent shareholding, but the precise allocation of the shares among individual sellers should be confirmed through official transaction records.
| Selling entity | Equity percentage transferred | Regulatory oversight mandate |
|---|---|---|
| National Social Security Fund (NSSF) | Individual allocation requires confirmation | Protect retirement savings and comply with applicable investment and pension laws |
| Unclaimed Financial Assets Authority (UFAA) | Individual allocation requires confirmation | Safeguard and administer unclaimed financial assets under its statutory mandate |
| Other participating state-linked institutions | Individual allocations require confirmation | Follow their enabling legislation, investment policies and applicable disclosure requirements |
The table highlights an important distinction: the combined value of the transaction does not reveal how much each institution received or whether each seller obtained fair value.
Parliament should require an institution-by-institution breakdown supported by audited accounts, share registers, sale agreements and relevant transaction disclosures.
Why an Independent Audit Is Necessary
An independent audit could establish whether the institutions received reasonable consideration and complied with their legal and governance obligations.
The review should cover the original IPO investments and the subsequent sale. Examining both stages would help establish how the institutions acquired their holdings, the investment decisions made and the financial results realised when the shares were transferred.
The Office of the Auditor-General could examine matters falling within its audit mandate, including the use of public resources and the financial records of relevant public entities.
The Capital Markets Authority and the Nairobi Securities Exchange also have relevant responsibilities within their respective regulatory and market functions. Their records could help clarify the transaction’s reporting, disclosure and trading arrangements.
The audit should examine valuation reports, board approvals, transaction-adviser assessments, brokerage fees and the identity of the parties involved. It should also establish whether conflicts of interest were identified and managed.
A sale price close to the original IPO offer price does not automatically prove that an institution obtained the best available return. Equally, a transaction cannot be declared improper simply because an institution sold shares within months of acquiring them.
The findings must be grounded in evidence, including the market conditions at the time of the sale and the valuation methods used.
What the Transaction Means for Kenya’s Energy Sector
Dangote’s entry into KPC could create opportunities for investment in pipeline capacity, petroleum storage and regional distribution. His wider energy interests, including the proposed refinery in Lamu, have placed Kenya within a broader strategy to expand petroleum infrastructure across Africa.
The potential commercial benefits are significant, but the government and the institutions involved must demonstrate that the ownership changes serve legitimate economic objectives without compromising public accountability.
KPC’s strategic importance makes transparent governance particularly necessary. Decisions affecting the company may influence long-term infrastructure investment, regional fuel distribution and the interests of other shareholders.
Parliament should therefore establish whether the sale complied with the relevant laws, whether the selling institutions followed their investment policies and whether the proceeds were properly recorded.
The inquiry should also distinguish between the government’s original privatisation of KPC and the later transfer of shares held by public institutions. Treating the two transactions as identical could obscure the different legal responsibilities involved.
Parliament Must Establish the Full Financial Record
The National Assembly has an opportunity to turn public concern into a clear, evidence-based assessment of the transaction.
A comprehensive review should establish the number of shares sold by each institution, the proceeds received, the valuation reports relied upon and the approvals granted. It should also clarify the role of relevant government agencies, institutional boards and market regulators.
Read Also: Pharmacy Board Looks to Shape Future of Pharmaceutical Practice
Any shortcomings identified should be addressed through appropriate oversight and corrective measures, with further investigations considered where the evidence warrants them.
Kenya can attract private investment while maintaining strong standards of transparency. The two objectives are compatible when transactions involving public resources are supported by credible valuations, clear documentation and effective oversight.
Dangote’s acquisition represents a significant development in the ownership of a strategic energy company. Its ultimate credibility, however, will depend on whether the institutions involved can demonstrate that the shares were transferred through a lawful process and at a price supported by reliable evidence.
Kenyans deserve a clear accounting of how the KPC shares changed hands, what each institution received and whether the transaction protected the financial interests those institutions were established to serve.