CMA Dangote Refinery Share Sale 2026: Approval Delay, Foreign Investor Rules, NSE Market Access

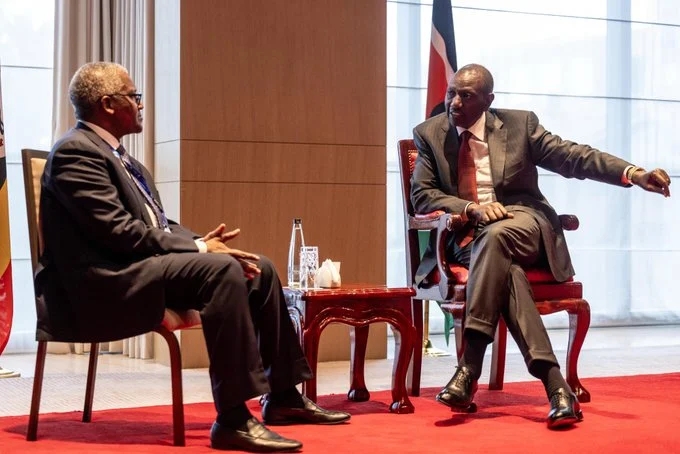
President William Ruto chats with billionaire Aliko Dangote. PHOTO/@WilliamsRuto/X
Kenyan investors seeking a stake in Nigeria’s Dangote Petroleum Refinery faced a regulatory delay before the Capital Markets Authority (CMA) approved local participation in the company’s initial public offering (IPO). The decision, announced on October 5, 2026, opened a route for eligible investors to access the offering through a financial instrument known as a global depository receipt (GDR).
The development has placed cross-border investment regulation under the spotlight, raising questions about the time required to approve foreign securities, the responsibilities of local investment intermediaries and the ability of East African investors to participate in major African capital-raising opportunities.
The refinery’s IPO is particularly significant because of its scale. Reuters reported that the offering could raise approximately $1.6 billion, making it one of the largest share sales in African corporate history.
The CMA’s official announcement confirmed approval of a short-form prospectus submitted by Renaissance Capital (Kenya) Limited, a licensed investment bank.
The decision illustrates the balance regulators must maintain between expanding investment opportunities and protecting the public from inadequate disclosure, unsuitable intermediaries and poorly understood financial products.
Dangote Refinery IPO: Why CMA Approval Matters
Dangote Petroleum Refinery and Petrochemicals launched its Nigerian IPO on September 14, 2026, with the offering scheduled to close on October 13, according to the CMA.
Although the shares were offered in Nigeria, potential investors in other African countries could not automatically participate under their domestic regulatory frameworks.
The Kenyan regulator’s approval was therefore necessary for the offering to be marketed locally through the approved GDR arrangement.
A Business Daily report on the approval explained that the local distribution of the investment instrument had initially been delayed while regulatory issues remained unresolved.
The CMA subsequently approved the short-form prospectus, enabling eligible Kenyan investors to participate through the authorised structure.
This distinction is important. The delay does not, by itself, demonstrate that the CMA opposed the refinery’s IPO or intended to prevent Kenyan investors from buying foreign shares. It demonstrates that a foreign public offering must satisfy the requirements applicable to the market in which it is being promoted.
For investors, the approval expands access to an opportunity outside Kenya’s domestic stock market. For regulators, it creates a responsibility to ensure that the investment is properly documented, distributed through authorised channels and understood by prospective buyers.
The offering also tests the ability of African capital markets to connect investors across national borders without compromising local regulatory safeguards.
CMA Approval Framework: Rules Governing Public Share Sales
The CMA operates under Kenya’s capital markets legislation, which establishes the framework for public offerings, securities listings, market intermediaries and investor protection.
The authority’s regulatory framework identifies the applicable laws and regulations, including the Capital Markets Act and the Capital Markets (Public Offers, Listings and Disclosures) Regulations, 2023.
These rules establish requirements for disclosures, prospectuses and the approval of securities offered to the public.
A prospectus is particularly important because it provides investors with information about the issuer, its business, financial position, the terms of the offer and the risks associated with the investment.
Investors need this information to make decisions based on evidence rather than promotional claims about a company’s size or commercial ambitions.
The CMA also publishes approval processes and checklists for securities issuances. These help issuers and intermediaries understand the documentation required for different types of transactions.
In a cross-border transaction, the regulator must consider the structure through which investors will acquire exposure to the foreign company. The approval of a local instrument does not necessarily mean that the foreign company’s underlying shares are being directly listed on the Nairobi Securities Exchange (NSE).
This is the distinction at the centre of the Dangote transaction.
Kenyan investors are accessing the offering through a GDR arrangement rather than a conventional domestic IPO in which a Kenyan company issues ordinary shares on the NSE.
Global Depository Receipts: Understanding the Investment Route
A global depository receipt is a negotiable certificate representing shares in a company, with a depository institution holding or administering the underlying securities under the relevant arrangement.
According to the CMA, GDRs can enable investors in one country to obtain exposure to a company based in another country without purchasing its underlying shares directly.
For the Dangote offering, Renaissance Capital (Kenya) Limited is responsible for the approved local arrangement, including appropriate custodial arrangements for funds received from investors.
The structure creates a channel through which eligible Kenyan investors can access an overseas equity offering using a regulated intermediary.
However, a GDR should not be treated as identical to an ordinary share purchased directly on the NSE. Investors need to understand the rights attached to the receipt, how the underlying shares are held, the applicable fees and the process for receiving any distributions.
They should also establish where the underlying securities are traded, how prices are determined and what arrangements apply if they wish to sell their investment.
Currency movements introduce another consideration. An investor using Kenyan shillings to acquire exposure to a Nigerian company may face exchange-rate effects in addition to changes in the company’s share price.
The CMA announcement provides the official starting point for understanding the approved Kenyan participation arrangement.
Cross-Border Investment Rules: Regulation Is Not the Same as a Capital Control
The Dangote case also highlights the difference between securities-market approval and restrictions on international capital transfers.
A regulator may require approval before a foreign security can be marketed to local investors. That process concerns the offering, the disclosures provided and the legal structure used to distribute the investment.
Capital controls, by contrast, generally refer to restrictions on the movement of money across national borders.
The two should not be confused. The reported delay in the Dangote share sale concerned the regulatory approval required for local participation; the available evidence does not establish that Kenya imposed a general prohibition on capital moving into the Nigerian offering.
Kenya’s capital markets regulatory framework includes rules governing foreign investors and public securities offerings. The precise requirements depend on the type of transaction, the instrument involved and the relevant regulatory provisions.
Cross-border transactions may also involve banking, foreign-exchange, custody, settlement and tax considerations. These requirements serve different purposes and should be assessed separately rather than described collectively as a blanket restriction on foreign investment.
For companies seeking investors across several African markets, this fragmented system can increase administrative costs and extend the time required to reach prospective buyers.
A transaction that has been authorised in one jurisdiction may still require additional approvals or documentation in another.
The result is a market in which investors may be interested in an offering but unable to participate until the necessary local arrangements have been completed.
NSE Market Liquidity: Opportunities for Kenyan Investors
The Dangote offering raises broader questions about liquidity and the development of Kenya’s capital markets.
Liquidity refers to the ability to buy or sell an investment without causing a substantial change in its price. A wider range of securities can give investors more opportunities to diversify, although the availability of additional investments does not automatically make a market more liquid.
Access to foreign companies through approved instruments could broaden the investment choices available to Kenyan households, pension funds and other eligible investors.
It may also encourage local investment firms to develop expertise in international custody, securities distribution and cross-border transactions.
However, the effect on the NSE itself requires careful interpretation. The approval of a GDR for a foreign offering does not establish that the underlying Dangote shares have been listed on the NSE or that trading volumes in domestic equities will increase.
Some Kenyan investors may allocate money to the foreign offering that they might otherwise have invested in local securities. Others may participate using funds previously held outside equities. The overall effect on domestic liquidity depends on investor behaviour, the size of subscriptions and subsequent trading arrangements.
The more immediate benefit is the potential expansion of investment access. Whether that translates into deeper domestic capital markets will depend on the development of reliable distribution channels and the ability of investors to trade efficiently.
Kenya’s Nairobi Securities Exchange remains central to domestic equity trading. Cross-border products can complement that market, but their structure and relationship with the local exchange must be clearly explained to investors.
Investor Protection: What Buyers Should Check Before Subscribing
The approval of an offering should not be interpreted as a guarantee that investors will make money.
Equity investments can lose value, and a large, internationally recognised company is not immune to commercial risks.
Dangote Petroleum Refinery operates in a capital-intensive industry exposed to crude oil prices, refining margins, demand conditions, financing costs and regulatory decisions. The company’s future performance will influence the value investors ultimately receive from their investment.
Prospective subscribers should read the approved offering documents and examine the company’s financial information, valuation, intended use of proceeds and principal business risks.
They should also establish the minimum investment, all transaction charges, applicable currency-conversion costs and the rules governing the sale or transfer of their receipts.
The identity and authorisation of the intermediary matter as well. Investors should use the approved channels rather than sending money to unverified individuals or relying on social media promises of guaranteed returns.
The CMA’s official website provides information about its regulatory mandate and authorised market participants.
The October 13 closing date announced for the Dangote IPO also makes timing important. Prospective investors should confirm the current offer status, subscription arrangements and any applicable deadlines directly with the authorised intermediary before making payment.
Africa’s Fragmented Capital Markets Face a Wider Test
The Dangote offering illustrates a broader challenge for African financial markets: the difficulty of allowing investors to access opportunities across borders through consistent, efficient regulatory arrangements.
Reuters reported on October 9 that the IPO had exposed obstacles to cross-border investment, including differences in national registration requirements and limited access channels for investors outside Nigeria.
The Reuters report on Africa’s cross-border investing barriers noted that the offering attracted interest from investors in countries including Kenya and Botswana, while the arrangements for accessing it remained fragmented.
Greater cooperation between regulators, exchanges, depositories and licensed investment firms could help reduce duplication and make regional investment products easier to distribute.
Such cooperation would not require regulators to abandon investor protection. Instead, it could focus on clearer approval procedures, compatible disclosure standards, efficient settlement systems and transparent responsibilities for intermediaries.
Regional initiatives aimed at integrating African financial markets could also create more opportunities for businesses to raise capital from investors beyond their home countries.
The challenge is to make cross-border participation easier without weakening the safeguards that protect investors.
Conclusion: Approval Opens a Door, but Investor Confidence Must Follow
The CMA’s approval of Kenyan participation in Dangote Petroleum Refinery’s IPO marked an important development in cross-border investment access. It followed a delay in local approval but ultimately established a regulated route for eligible Kenyan investors to participate through a GDR.
The episode highlights the importance of clear prospectuses, authorised intermediaries, effective custody arrangements and predictable approval processes.
It also demonstrates why regulatory delays should be examined using documented evidence rather than automatically interpreted as capital controls or opposition to foreign investment.
For Kenya, the longer-term opportunity lies in building a capital market that protects investors while giving them access to a wider range of domestic and international assets.
Achieving that balance will require cooperation between regulators, investment firms and regional exchanges, alongside better public understanding of the risks involved in buying securities.
The Dangote offering provides a practical test of that ambition. Its wider significance will depend not only on the money raised, but also on whether investors can participate transparently, understand their exposure and trade through reliable channels.