CMA Commercial Paper Regulations: What Kenyan Companies and Investors Need to Know About Corporate Debt Oversight

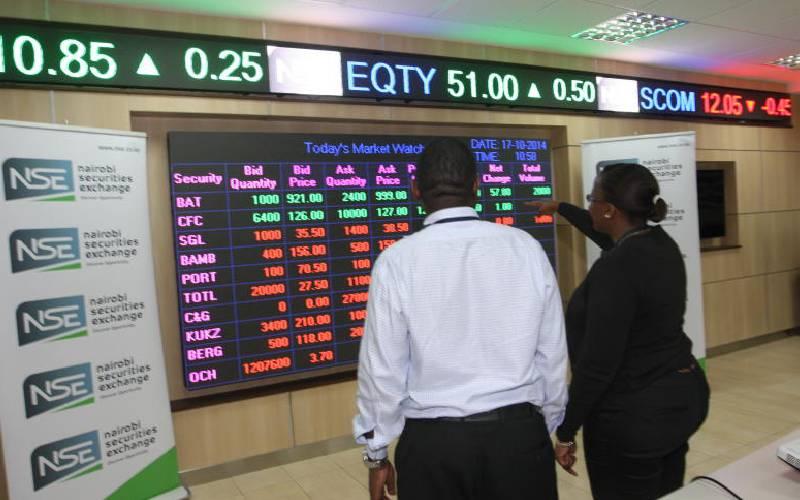
Corporate debt market remains an important source of financing for businesses seeking alternatives to conventional bank borrowing. However, the risks associated with short-term debt instruments continue to place investor protection, financial transparency and regulatory oversight at the centre of capital markets supervision.
The Capital Markets Authority (CMA) is responsible for supervising securities issuance, regulating market participants and protecting investors through the Capital Markets Act and supporting regulations. Its regulatory framework provides the foundation for companies seeking to raise money through commercial paper and corporate bonds, as well as investors considering exposure to privately issued debt.
The discussion surrounding commercial paper regulation in 2026 has also brought attention to additional safeguards, including credit rating requirements, independent trustee oversight, escrow repayment arrangements and regular financial disclosures. However, a new 2026 CMA circular introducing all these measures as universal requirements has not been independently verified against the Authority’s published regulatory documents.
The distinction matters because investors, companies and financial institutions need to understand which obligations are already established under Kenyan law and which additional safeguards would require a formal regulatory instrument.
CMA’s Regulatory Mandate and Corporate Debt Oversight
The Capital Markets Authority derives its mandate from the Capital Markets Act, Cap 485A, which establishes the institution as the regulator responsible for developing and supervising an orderly, fair and efficient capital market.
Section 11 outlines the Authority’s objectives and regulatory responsibilities, including protecting investor interests, promoting market development and ensuring securities are issued and traded within an orderly regulatory environment.
The provision also establishes the Authority’s powers to supervise market participants, investigate relevant activities, issue directions and enforce compliance with the Act and applicable regulations.
These responsibilities provide the legal foundation for oversight of corporate debt instruments, including commercial paper and bonds issued by companies.
However, Section 30 and Section 30A should not be treated as interchangeable provisions. Section 30 addresses the prospectus requirements applicable to public securities offers, while Section 30A provides for the publication of information memoranda. Section 30B and Section 30C address restricted public offers and information notices respectively.
The distinction is important when interpreting regulatory announcements because statutory provisions must be applied according to their actual legal purpose.
Commercial Paper Offers Companies an Alternative Source of Financing
Commercial paper is a short-term debt instrument through which companies raise money to finance operational requirements, working capital and other immediate business obligations.
Unlike equity financing, which involves selling an ownership interest in a company, commercial paper represents a borrowing arrangement. The issuing company undertakes to repay investors according to agreed maturity and payment conditions.
The CMA recognises commercial paper as a capital markets product. Its capital markets products guide explains that commercial papers are short-term debt instruments issued by companies to raise funds and are not transferable or listed on a securities exchange.
This characteristic distinguishes commercial paper from conventional corporate bonds, which are generally longer-term debt instruments.
Businesses may find commercial paper attractive because it can provide access to funding without requiring them to negotiate conventional long-term bank facilities. Investors, meanwhile, may consider the instruments as part of their fixed-income investment strategies.
Nevertheless, the repayment obligation creates risks, particularly where an issuing company experiences declining revenues, liquidity shortages or difficulties refinancing existing liabilities.
A company can appear financially stable when issuing debt but experience significant changes before the maturity date. Investors therefore need reliable information about its financial position and ability to meet contractual obligations.
Credit Ratings and Financial Risk Assessment
Credit ratings are an important part of corporate debt assessment because they provide an independent opinion about an issuer’s ability to meet its financial obligations.
A rating agency evaluates factors such as the company’s financial performance, debt exposure, cash flow, business environment and repayment capacity.
For investors considering commercial paper, this information can help distinguish issuers with different levels of credit risk.
Kenya has a regulatory framework governing credit rating agencies through the Capital Markets (Credit Rating Agencies) Regulations, 2023. The CMA also publishes information about its recognised and regulated market participants.
However, the existence of credit rating regulation does not automatically establish a universal investment-grade threshold for every commercial paper issuance.
Any claim that all issuing companies must obtain a particular minimum rating before accessing the market should be supported by the applicable regulation, CMA directive or formal circular.
A transparent rating framework would nevertheless strengthen market confidence by improving the availability of comparable information and helping investors understand the risks associated with different debt offerings.
Trustee Oversight and Repayment Protection
Independent oversight is another important consideration in corporate debt governance.
Trustees can provide an additional layer of protection in debt arrangements by monitoring compliance with agreed terms, overseeing specified security arrangements and representing investors where the applicable transaction structure provides for such responsibilities.
Their role becomes particularly important where an issuer has multiple investors whose interests may be affected by delayed repayments, financial restructuring or a failure to meet contractual obligations.
Escrow accounts can also provide additional repayment protection when appropriately structured. Under such arrangements, specified funds are held separately and released according to agreed contractual conditions.
For short-term debt, an independently administered repayment account could help ensure that money reserved for maturity settlements is not diverted to unrelated business expenses.
However, it would be inaccurate to describe trustee-managed escrow accounts as a newly introduced universal CMA requirement without an identifiable legal instrument establishing that obligation.
Companies and investors should therefore examine the actual offer documents, repayment arrangements, security provisions and trustee responsibilities before entering into a transaction.
Financial Reporting and Corporate Solvency Disclosures
The financial position of an issuing company is central to determining whether it can honour its debt obligations.
Investors require information about revenue performance, operating expenses, outstanding borrowings, assets, liabilities and cash flow.
The Capital Markets (Public Offers, Listings and Disclosures) Regulations, 2023 establish disclosure requirements for securities offered to the public and securities seeking admission to the relevant market segments.
These requirements are intended to give investors access to material information before making investment decisions.
Financial reporting is particularly important where companies depend on short-term borrowing to maintain their operations. An issuer with significant debt obligations may face pressure if its cash flow deteriorates or its creditors demand repayment within a limited period.
Quarterly solvency reporting could provide an additional monitoring mechanism if formally required by the regulator or incorporated into applicable issuance conditions.
Such disclosures could include:
- Current assets and current liabilities.
- Total outstanding borrowings.
- Debt-to-equity ratios.
- Operating cash flow.
- Upcoming debt maturity obligations.
- Material changes affecting the company’s ability to repay investors.
These indicators would help investors assess whether an issuer’s financial position has changed significantly since the original debt offer.
It is important, however, to distinguish between reporting obligations already established by applicable regulations and additional quarterly disclosure proposals that have not been independently verified as universal CMA requirements.
Public Debt Promotions and Regulatory Compliance
The marketing of corporate debt instruments also requires careful regulatory attention.
Companies seeking money from investors must understand the distinction between private fundraising arrangements and securities offers made to the public.
The Capital Markets Act and the applicable public offers regulations provide the legal framework governing securities offers, disclosure obligations and regulatory approval.
Section 30 of the Act addresses prospectus requirements for public offers, while Section 30A addresses information memoranda. The relevant provisions require issuers to comply with the applicable disclosure framework.
The 2023 Public Offers, Listings and Disclosures Regulations provide further requirements governing public offers and disclosure arrangements.
Consequently, companies should not assume that promotional material distributed through social media, websites, investment groups or other communication channels automatically falls outside securities regulation.
Where an activity amounts to an offer of securities to the public, the relevant statutory and regulatory requirements must be considered.
Section 11 also provides CMA with statutory enforcement powers for breaches of the Act, applicable regulations and regulatory directions. Depending on the circumstances and the applicable provisions, enforcement measures can include financial penalties and other regulatory interventions.
Investors should be cautious about advertisements promising unusually high returns without providing clear information about the issuer, maturity arrangements, repayment capacity and applicable regulatory approvals.
The Authority’s investor information and protection guidance provides useful advice on dealing with licensed entities, assessing investment products and avoiding fraudulent investment schemes.
What Stronger Corporate Debt Oversight Could Mean for Investors
A more comprehensive corporate debt oversight framework could have important implications for Kenya’s investment environment.
Institutional investors, including pension funds, insurance companies and investment managers, need reliable information when assessing corporate debt exposure.
Greater transparency could improve their ability to compare issuers, assess repayment risks and identify warning signs before financial difficulties become severe.
Retail investors would also benefit from clearer explanations of the differences between commercial paper, corporate bonds, Treasury bills and other fixed-income products.
Commercial paper should not be treated as equivalent to a government security. Unlike Treasury instruments issued by the Government, corporate debt carries the repayment risk of the issuing company.
Investors must therefore assess the financial strength of the borrower rather than relying exclusively on the advertised interest rate.
For businesses, stronger disclosure requirements could increase the cost and administrative demands associated with issuing debt. Companies might need to invest more in financial reporting, independent assessments and compliance systems.
However, improved transparency could also strengthen investor confidence and support the development of a more credible corporate debt market.
Regulatory Framework Governing Commercial Paper in Kenya
The following table outlines the relevant legal framework and distinguishes established regulatory provisions from additional safeguards that should not be presented as confirmed universal requirements.
| Debt governance pillar | Statutory or regulatory framework | Market and issuer requirements |
|---|---|---|
| Credit rating oversight | Capital Markets (Credit Rating Agencies) Regulations, 2023 | Provides a regulatory framework for credit rating agencies. A universal investment-grade threshold for all commercial paper requires specific confirmation. |
| Public offer disclosures | Capital Markets Act and 2023 Public Offers, Listings and Disclosures Regulations | Issuers must observe applicable disclosure and approval requirements when offering securities to the public. |
| Trustee oversight | Applicable securities regulations and transaction documents | Trustee responsibilities depend on the instrument and relevant legal and contractual arrangements. |
| Escrow repayment arrangements | Relevant transaction documents and applicable regulatory requirements | Escrow accounts can strengthen repayment protection where properly established, but a universal new mandate has not been verified. |
| Financial reporting | Public Offers, Listings and Disclosures Regulations, 2023 | Financial disclosures help investors evaluate issuers and assess material financial risks. |
| Regulatory enforcement | Section 11 of the Capital Markets Act | CMA has statutory enforcement powers for breaches of the Act, regulations and applicable directions. |
What Companies and Investors Should Watch Next
The next important consideration is whether CMA publishes a formal circular or additional regulatory guidance specifically addressing commercial paper issuance and corporate debt oversight.
Companies intending to raise money through debt instruments should monitor the Authority’s official regulatory framework and circulars and ensure their issuance structures comply with existing requirements.
Investors should also obtain and examine the relevant information memorandum, financial statements, credit assessments where available, repayment conditions and any applicable security arrangements.
The CMA’s approvals process and regulatory checklists provide a useful starting point for businesses seeking clarity on the requirements governing securities issuance.
Any new directive introducing mandatory ratings, escrow structures or additional reporting deadlines should be assessed against its publication date, legal authority, scope and implementation provisions.
Kenya’s corporate debt market can benefit from stronger transparency and investor protection, but effective regulation must be supported by clearly published rules and enforceable obligations.
For investors and businesses alike, the central issue is not simply how much money a company can raise, but whether the market has sufficient information and safeguards to assess its ability to repay.