Digital Lenders Risk-Based Pricing Review 2026: CBK Licensing Audits, SME Credit Expansion, Default Risks

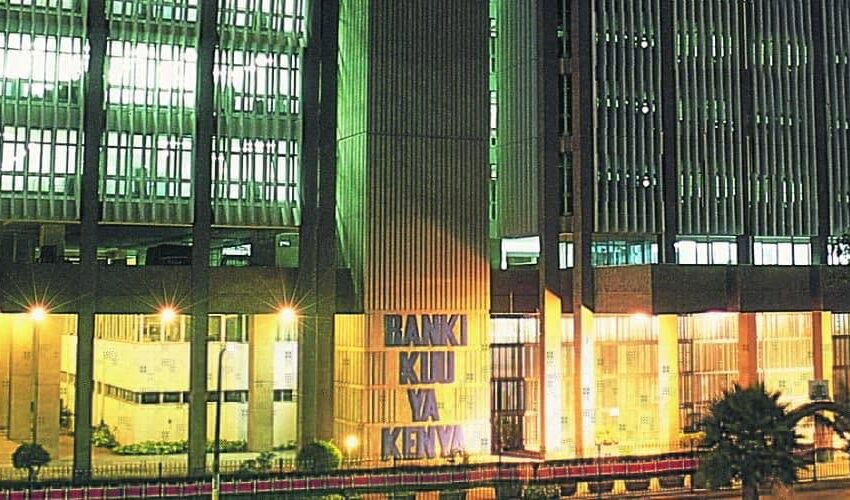
Central Bank of Kenya (CBK). IMAGE: Courtesy
Digital lending market is entering a more closely supervised phase in 2026 as the Central Bank of Kenya (CBK) expands licensing, strengthens consumer-protection oversight and pushes lenders towards more transparent approaches to credit risk.
The changes come against a sharp increase in digital borrowing.
CBK reported in September 2026 that the number of licensed Digital Credit Providers (DCPs) had reached 281 after the regulator approved 29 additional providers. The latest licensing round followed more than 900 applications received since March 2022.
The regulator said its review of applicants focuses on business models, consumer protection and the fitness and propriety of shareholders, directors and management.
Read Also: Top Comoros Official Hospitalized in Nairobi Amid Rising Tensions in Moroni
That scrutiny matters because digital lenders now occupy a much larger part of Kenya’s credit market than they did when CBK first received powers to regulate previously unregulated digital lenders.
The latest figures show that licensed DCPs had issued 9,596,509 loans worth KSh165.1 billion by August 2026. The products include short-term personal loans, education loans, asset financing, development loans and business credit.
The expansion is creating a policy challenge for CBK: maintaining access to fast credit while ensuring that pricing, risk assessment, data use and debt collection remain within the regulatory framework.
CBK Tightens Digital Lending Oversight
Kenya’s digital credit regulation began taking shape after Parliament amended the Central Bank of Kenya Act in 2021, giving CBK authority to license and supervise previously unregulated digital credit providers.
The CBK Digital Credit Providers Regulations were gazetted in March 2022 and established the framework for licensing and oversight of the sector.
The regulatory objective was not simply to increase the number of licensed lenders.
CBK’s intervention followed concerns over high loan costs, aggressive debt collection and misuse of borrowers’ personal information.
Those issues remain central to the regulatory debate in 2026.
The regulator’s September licensing announcement again highlighted consumer protection and business-model reviews while warning that members of the public should report unregulated DCPs.
Consumers can also check the official CBK directory of licensed digital credit providers before borrowing from an app or online lender.
That verification step has become increasingly important as the number of licensed providers grows and new lending applications enter the market.
Risk-Based Pricing Becomes More Important
Risk-based pricing is increasingly relevant to Kenya’s wider credit market because lenders face different levels of default risk across borrowers.
A customer with a strong repayment history, stable income and reliable credit information presents a different risk profile from someone with limited borrowing history or repeated defaults.
A lender therefore needs to balance three variables: the probability that a borrower will repay, the cost of providing the loan and the return required to compensate for credit risk.
CBK has separately introduced a revised Risk-Based Credit Pricing Model for the banking sector. The model followed a public consultation process and was designed around more transparent risk-based lending.
The distinction is important.
The revised RBCPM is a banking-sector framework, rather than a blanket interest-rate formula imposed on every licensed digital lender.
Digital Credit Providers continue to operate under their own regulatory requirements, while CBK’s broader 2026 work on non-deposit-taking credit providers is aimed at strengthening the framework covering institutions that provide credit outside the deposit-taking banking system.
This means the conversation about risk-based pricing should not be interpreted as CBK imposing the banking-sector RBCPM directly on every DCP.
Read Also: KNEC Grade 10 Assessment 2026: Guidelines, Timelines & School Requirements
Instead, the wider regulatory direction points towards stronger transparency, better risk management and more disciplined credit assessment across Kenya’s financial system.
New Rules Expand The Regulatory Framework
CBK has also been developing the Non-Deposit Taking Credit Providers regulatory framework, following amendments to the CBK Act under the Business Laws (Amendment) Act, 2024.
The change is significant because the term “digital” had created a narrower impression of the market than the regulator intended.
CBK’s regulatory impact assessment explains that the 2024 amendment replaced the term “digital” with “non-deposit taking” in order to broaden the framework and address uncertainty over which credit providers fall under the CBK mandate.
The proposed framework also seeks to address weaknesses identified after several years of digital-lending regulation.
High borrowing costs, poor debt-collection practices and abuse of personal information were among the original concerns behind regulation of DCPs.
The new approach therefore places the digital-lending market within a broader regulatory architecture rather than treating smartphone-based lending as an isolated fintech activity.
SME Working Capital Drives Credit Demand
Digital credit has become particularly relevant to small businesses that require quick working capital.
A small retailer may need money to replenish stock before receiving payment from customers. A trader may require temporary financing to purchase inventory. A service provider may need funds to meet an unexpected operating expense.
Traditional bank lending can involve documentation, collateral requirements and longer approval processes.
Digital credit can provide a faster alternative.
CBK’s March 2026 market perceptions survey showed that commercial banks expected stronger private-sector credit growth during the year, with demand particularly supported by SMEs, small traders and micro enterprises. Respondents also identified working-capital requirements, restocking and business expansion as drivers of credit demand.
The development shows why digital lending cannot be viewed solely through the lens of consumer borrowing.
Business loans are now part of the DCP market.
CBK reported in July that licensed DCPs offered products including asset financing and business loans alongside personal and education credit.
That creates an important opportunity for Kenya’s small-business economy.
Short-term credit can help a business bridge cash-flow gaps without requiring the owner to wait for a traditional loan approval.
The risk is that expensive or repeatedly rolled-over short-term borrowing can also weaken a business’s cash flow if revenue fails to keep pace with repayments.
Digital Credit Growth Raises Default Questions
Rapid expansion in lending inevitably brings greater attention to repayment performance.
CBK’s 2025 Bank Supervision Annual Report showed just how quickly the DCP market had expanded.
Gross outstanding loans from DCPs almost doubled from KSh55.2 billion in December 2024 to KSh110.1 billion in December 2025, representing 99.6 percent growth. During the same period, the number of licensed providers increased from 85 to 195.
The average number of loans also increased by 71 percent to 6.74 million in December 2025 from 3.9 million a year earlier.
The growth creates a larger pool of borrowers whose repayment behaviour can influence future lending decisions.
A lender relying on automated risk models will typically examine information such as previous repayment patterns, outstanding obligations and other available credit information.
A borrower with repeated late payments may consequently face different credit decisions from someone with a consistent repayment record.
Risk-based lending is therefore closely connected to accurate credit information.
Credit Reference Bureaus Become Central To Automated Lending
Credit Reference Bureaus (CRBs) provide one of the most important pieces of infrastructure behind risk-based lending.
The CBK credit-information framework allows licensed CRBs to collect and provide credit information that helps lenders evaluate borrowers. CBK notes that financial institutions have a duty to provide accurate credit information, while consumers have the right to dispute information contained in their credit reports.
Digital lenders also have specific obligations under the DCP Regulations.
The regulations require DCPs to disclose both positive and negative credit information to licensed CRBs where reasonably required. They also require information submitted to be timely, complete and accurate.
That requirement is particularly important as automated lending becomes more sophisticated.
A computerised credit-scoring system can process thousands of applications quickly, but the quality of its decisions depends partly on the quality of the information entering the system.
Incorrect information can therefore have consequences beyond one loan application.
A borrower wrongly classified as a high-risk customer could face reduced access to credit or less favourable terms.
Borrower Protection Remains A Regulatory Priority
Credit scoring cannot be separated from consumer protection.
Kenya’s digital-lending regulations prohibit several aggressive debt-collection practices, including threats, abusive language, public disclosure of personal information and unauthorised contact with people in a borrower’s phonebook.
The rules also require digital credit providers to establish complaints-handling mechanisms.
A customer must have a clear channel through which a dispute can be raised, while unresolved complaints are subject to a prescribed resolution period.
These provisions become increasingly important as more credit decisions are automated.
A borrower should be able to understand who is providing the loan, what the financial obligations are and where to raise a complaint when something goes wrong.
Data protection is equally important.
Digital lending applications can process significant amounts of customer information, making responsible handling of personal data a core part of regulatory compliance.
Is There An Interest Rate Cap For Digital Lenders?
One of the most common misconceptions surrounding digital lending is the assumption that Kenya has a single statutory interest-rate cap applicable to every digital loan.
The regulatory framework is more complicated.
CBK’s digital-credit regulations focus heavily on disclosure, licensing, consumer protection, debt collection, credit information and responsible conduct.
The revised Risk-Based Credit Pricing Model, meanwhile, was issued specifically for the banking sector. Its structure is based on a reference rate and a premium reflecting factors including operating costs, shareholder return and borrower risk.
That means the phrase “digital lender interest rate cap CBK” should be treated carefully.
The key regulatory question is not simply whether every digital loan carries the same maximum interest rate.
It is whether the provider is licensed, whether charges are properly disclosed, whether its practices comply with applicable CBK requirements and whether borrowers are protected from prohibited conduct.
The regulatory framework is evolving, making it important for consumers and businesses to distinguish between banking-sector pricing reforms and the separate rules governing non-deposit-taking lenders.
Licensing Is Becoming A Competitive Filter
CBK’s licensing programme is also changing the structure of the industry.
The September 2026 announcement brought the licensed DCP population to 281. CBK said it had received more than 900 applications since March 2022 and continued to review applicants at different stages of the process.
The regulator’s updated September 2026 DCP directory provides the latest list of licensed providers.
Licensing gives customers an important reference point.
A business or individual searching for a digital loan can confirm whether the provider appears in CBK’s official records before submitting personal information or accepting credit terms.
The expansion of the licensed market also means compliance will become increasingly important for lenders seeking long-term survival.
Technology alone is no longer enough.
Providers must demonstrate that their lending models, management structures, consumer-protection systems and operational practices meet regulatory expectations.
The Next Stage Of Digital Lending
Kenya’s digital lending market is moving from rapid expansion towards a more mature phase.
The numbers show strong demand: DCPs had issued more than 9.5 million loans worth KSh165.1 billion by August 2026.
The challenge now is ensuring that expansion remains sustainable.
Read Also: Kenyan marathoner remanded over Ksh8 million land fraud case
Lenders need accurate risk models to distinguish between customers who can safely service credit and those who may struggle with repayment.
SMEs need affordable working capital without becoming trapped in expensive short-term borrowing cycles.
CRBs need accurate information to support responsible automated decisions.
Consumers need transparency over the real cost of borrowing and meaningful ways to challenge incorrect information.
CBK, meanwhile, faces the task of supervising an industry that is expanding faster than traditional financial-service models.
The direction of regulation points towards a more structured digital-credit market, where licensing, consumer protection, credit-information sharing and responsible risk assessment increasingly determine how lenders operate.
Digital credit will likely remain an important source of short-term financing for Kenyan households, traders and SMEs.
The bigger question in 2026 is no longer whether Kenyans will borrow through digital platforms.
It is whether the next generation of digital lending can combine speed, affordability, accurate risk assessment and strong consumer protection without weakening the financial health of the borrowers it is designed to serve.